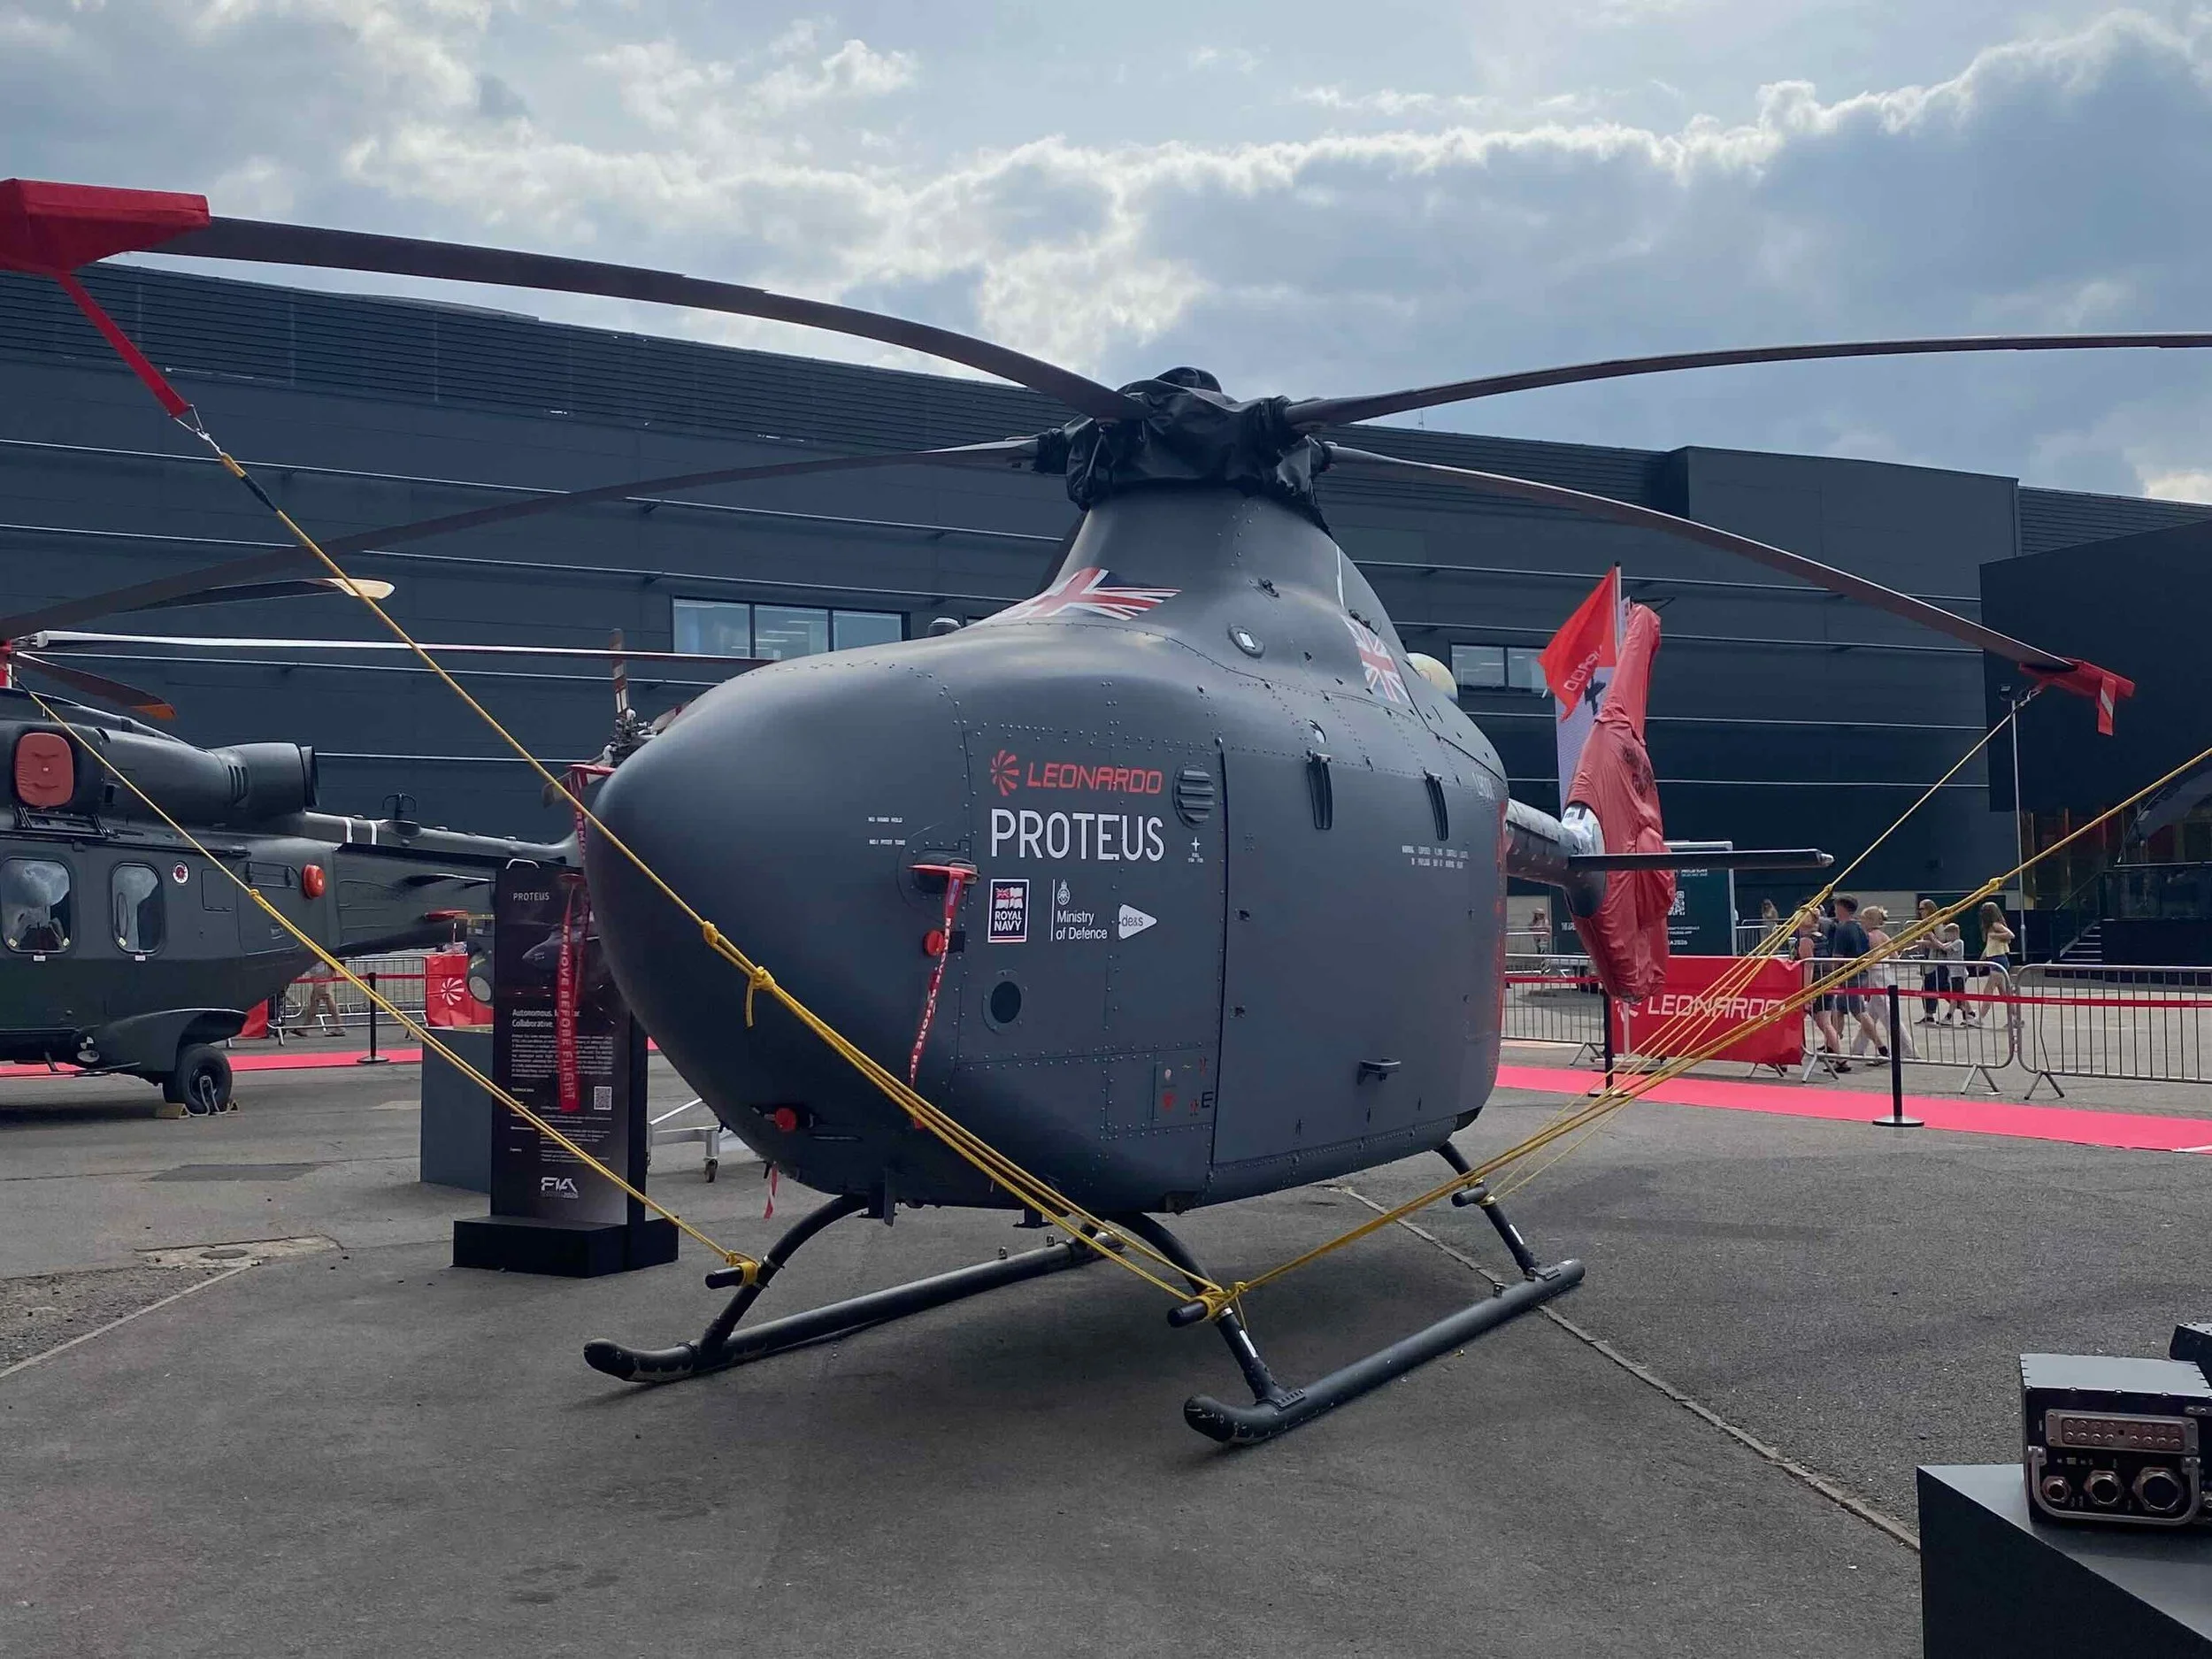
You are probably reading this on a phone or laptop connected to the internet. Yet, did you know that the internet's roots lie in ARPANET, a network funded by the US Department of Defense's research agency from the late 1960s? It ran on packet switching, a concept developed in parallel by Donald Davies at Britain's National Physical Laboratory. And the web you are browsing was invented in 1989 by a British scientist, Tim Berners-Lee, at CERN.
At the same time, if you are using a smartphone and used maps today, or ordered food to your door. Both rely on GPS, a system the US military built for its own navigation needs. The US National Academies describe it plainly as a ‘dual-use’ system, designed for defence and opened to everyone else.
The uncomfortable point for some, is that much of the technology we depend on every day was paid for by defence budgets and shaped by our own security needs. Yet in Britain and across Europe, many investors, banks, corporates and a good number of the general public still treat defence as something to keep at arm's length, in the same category as tobacco and gambling. For too many it’s seen as a ‘sin stock.’
That view made a kind of sense when the threats felt distant. Yet they no longer are. Drones are crossing NATO borders, hybrid attacks are hitting European infrastructure, and AI is lowering the cost of attacking us. Our caution, and in some cases our virtue signalling, is now adding to our risk rather than reducing it.
And the issue is, ask anyone about security and, as an example, more policing on the streets, and they will say that they want that. Yet, defence, or at least what we see of it, which is the hardware, and there is generally a firm no. The issue here is that local security is concrete and visible. National defence is abstract and distant.
We need an open, honest conversation about investing in security and resilience, which for most people still means defence and dual-use technology, when cyber security and other methods are already being used in hybrid ways.
The money has arrived. The question is whose money.
Defence tech investment is at a record high, but for the first time US investors now fund more of Europe's defence startups than Europeans do.
That is the headline finding in The State of Defence Tech 2026, published by Resilience Media and Dealroom last month in October 2026, with data to September. Consider the scale first:
Defence startups across NATO countries raised $27.1 billion in venture capital in 2026, already 1.9 times the total for 2025.
European defence startups raised $7.4 billion, their most active year on record.
Defence now takes 11.1% of all European venture funding, up from 0.5–1% before 2020.
The argument that ‘nobody will fund defence’ no longer holds. Capital is flowing. But let’s look where it comes from.
In 2020, US investors provided 17% of European defence tech funding and European investors 78%. In 2026 so far, US investors provide 47% and European investors 44%. The lines have crossed. Every one of the largest European rounds this year, at Helsing, Quantum Systems, ICEYE and Stark, included US capital.
The UK picture is better than it was, but small against the scale of the opportunity. British defence startups raised $932 million in 2026, third in Europe behind Germany ($3.5 billion) and Finland ($1.2 billion). The UK recorded its first two megarounds, at Cambridge Aerospace and Kraken Technology. Yet, as Politico reported, US defence tech firms raised $19.6 billion over the same nine months.
The issue is not that the UK and Europe lack capital to invest or innovative companies to invest in, but that we have built systems that keeps our capital away from them. UK pension schemes hold £3.2 trillion, yet the Pensions Policy Institute estimates that just 6% is invested in UK productive assets such as private equity. The BVCA has found that UK pension funds supply only 3% of the pension money invested in British private capital; the rest comes from overseas. Across the EU, households hold around €10 trillion in bank deposits, and roughly €300 billion of European savings flows out to non-EU markets every year. As Ursula von der Leyen put it in September, “there is no shortage of technology or savings” in Europe. What we collectively lack is the will and the machinery to deploy them. In defence, the result is now measurable: US investors provide 47% of European defence tech funding, against 44% from Europeans.
And these figures should concern not just the public, but every UK and European Board. Since 2020, European defence primes have taken part in just 28 venture rounds in European defence startups. That covers Safran, Airbus, MBDA, Saab, BAE Systems and others combined, over six years. Beyond the primes, the corporates actively backing European defence startups include Axon, a US company. Where are the British ones?
So the real issue is not whether capital arrives. It is who owns the equity, the upside and the influence when it does. A country that relies on others to finance its security technology should not be surprised when others shape its direction.
The barrier is perception and reputation, not regulation
The UK has spent much of the past year arguing about ESG rules, when the evidence points to a different set of blockers: perception and reputational fears.
The political debate has been loud, with more than 100 Labour MPs and peers urging banks and pension funds to treat defence as an ethical investment. The Defence Secretary has called defence an ’ethical investment’ and promised to tackle the blockers.
But a RUSI report from September 2025 found that ESG rules are not what is blocking funding for UK defence. Exclusions are choices that investors make, not obligations that regulators impose. The commercial reason is clear to see: sustainable funds that hold defence stocks find it harder to market themselves to retail investors. That is a perception problem, priced in.
Politico's October investigation shows how it works in practice:
The restrictions are contractual. They can be written into limited partnership agreements, the contracts that govern how funds use investors' money.
Founders route around them. Quantum Systems' co-founder said he had to set up a separate company to build lethal drones after investors objected. That company, Stark, is now one of Europe's leading defence startups. The caution did not stop the capability being built. It only decided who captured the value.
Banks act on it. A venture investor told Politico that Revolut closed a portfolio company's account after learning it made drones. Revolut said defence is on its list of restricted industries, adding: ‘This may evolve in the future.’
Some in the industry are saying what they see, that a more dangerous world will change perceptions on its own, and that rising threats will do the persuading investors have so far resisted. Thought I’d challenge that. Waiting for a crisis to change perceptions is not a strategy. A view that shifts because of fear can shift back when the fear fades. What lasts is a reputational case that investors can defend to their own stakeholders, grounded in governance, export controls and transparency rather than in euphemism. Calling defence ‘resilience’ will not fix a trust problem. Explaining clearly what you fund, why, and under what controls will.
What the UK has, and why it is worth protecting
For the record, The UK does not start from weakness. It has the talent, the institutions and the track record to lead in security and resilience technology, if it thinks strategically, incentivises investors so that as a nation it can be reliant on the outcomes that better suit ourselves. What the UK has includes:
A record of invention. Packet switching and the World Wide Web both have British innovators. The pattern of defence and civil innovation feeding each other is not new to this country.
Deep tech clusters. London, Cambridge, Oxford and other locations all rank among Europe's top ten hubs for defence venture investment, according to the Dealroom data.
Momentum. The UK led Europe in venture funding for defence, security and resilience startups in 2025, with $2.9 billion of an $8.7 billion total, on Dealroom and NATO Innovation Fund figures. In 2026 it recorded its first two defence megarounds.
Exits. The only European company among the ten largest defence startup exits of all time is Arqit, a British quantum encryption business.
People. Founders and commercial leaders with military or defence ministry backgrounds in European defence tech come mostly from the UK, Germany and France. That experience matters: it is how startups learn to sell to governments.
These are assets, and assets need looking after. Talent leaves when capital is easier to find elsewhere, hence the risk we have of UK innovation moving to the US to scale because of the capital and culture that they have. At the same time, companies redomicile when their largest shareholders sit in another market. Intellectual property follows ownership. If British capital stands aside, British innovation will still be built. It simply will not stay British.
The threat has changed, and AI has changed it fastest
Security is no longer only about tanks, frigates and missiles. The most immediate threats to British companies, infrastructure and citizens increasingly arrive through software, and AI is making them cheaper, faster and harder to attribute.
The physical threats are real enough. Helsing’s co-founder, Torsten Reil, points to drone incursions over Poland and Estonia as the moment that “started to sharpen people’s minds” (Dealroom). But the digital front is where physical and cyber now meet. In December 2025, an attack on Poland’s energy grid, which the UK and EU later attributed to Russia’s FSB, could have left 500,000 people without electricity had it succeeded.
The UK’s National Cyber Security Centre is transparent and direct about where this is heading. Its recently published 2026 Annual Review, judges that by 2028 China, Russia and other states will highly likely be using AI routinely in their cyber operations. It also judges that AI-powered malware will highly likely have been used in a ransomware attack on UK critical national infrastructure by then.
This is no longer theoretical. In November 2025, Anthropic reported disrupting a cyber espionage campaign that it attributed with high confidence to a Chinese state-sponsored group. The attackers manipulated an AI system into running most of the operation against around 30 organisations, with humans stepping in only at key decision points.
The economic cost is already visible, with the NCSC estimating that malicious cyber activity costs UK organisations £14.7 billion a year, roughly equivalent to the size of the UK’s entire cyber security sector. The 2025 attack on Jaguar Land Rover alone cost the company around £196 million and, the NCSC says, contributed to UK growth of just 0.1% in the third quarter. One company’s breach showed up in national GDP.
Most important for this argument, the NCSC judges cyber espionage highly likely to be the most significant cyber threat to the UK’s long-term growth, with knowledge-intensive sectors the most attractive targets. Britain’s innovation is exposed on two fronts: others are buying the equity, and others are trying to steal the IP.
The NCSC’s chief executive, Richard Horne, puts it plainly: “AI did not create these cyber security weaknesses; it revealed them.” The lesson for investors and boards is simple. The same AI tools that power your productivity can be turned against your networks, your supply chains and your customers. Defending against that requires security and resilience technology: threat detection, secure communications, quantum-safe encryption, resilient navigation and timing. Much of it is dual-use. All of it needs capital.
The companies building it are exactly the ones a reputational filter screens out. A blanket exclusion on ‘defence’ does not keep your portfolio clean. It leaves it, and the economy it depends on, less protected.
What has to change: five moves
The fix is not another round of political pressure on rules and regulation. It is a deliberate shift in how investors, corporates and government build and communicate the case for security investment.
Replace blanket exclusions with defined standards. Investors should decide what they will and will not fund, and say so publicly: which weapons, which end users, which export controls. A clear, governed position can be defended to members and customers. A vague exclusion only defers the question.
Bring UK corporates in on the demand side. The current debate focuses too much on institutional - pension funds and government money. The missing player is the British corporate, investing capital and, more importantly, knowledge through venture arms and partnerships. Banks, insurers, energy, telecoms and logistics firms all depend on security technology. They should help build it, not only buy it.
Treat de-banking as a strategic risk. When a regulated defence supplier cannot keep a bank account, that is a resilience issue, not a compliance footnote. Banks need clear sector policies, and the government should ask how many British security startups face this.
Measure what matters. The government's 2025 Industrial Strategy pledged to halve the UK's defence venture funding gap with the US by 2035, yet it could not give Politico its own estimate of the gap. Ministers should publish the baseline, track it, and add a second measure: the share of UK defence tech equity held by UK investors.
Move at the speed of the threat. The MoD's fast-track route now averages around 60 days to contract, against roughly six years for major platform competitions. A contract is the strongest signal an investor can receive. Scale the fast routes, and the private money will follow.
None of this asks anyone to abandon their values. It asks them to apply those values with precision. Security is a precondition for the ‘social’ in ESG, not its opposite.
The question for every board
Reputation is strategic capital. Right now, Britain and Europe are spending it on caution, and the return is going to investors who are, in one investor's words to Politico, ‘a bit less queasy’.
So here is the question I would put to every investment committee, corporate board and pension trustee. If you would not invest in the technology that protects your networks, your supply chains and your country, who do you expect to own it and lower the risk that you are exposed to and price in to your operating costs? And on whose terms will you buy it back?
I would welcome your view, especially if you disagree.
Frequently asked questions
Is it ethical to invest in defence? That depends on what you fund and under what controls, which is why defined standards beat blanket exclusions. UK sustainable finance rules do not prohibit defence investment; exclusions are a choice made by each investor.
Do ESG rules stop UK investors funding defence? No. A RUSI report found ESG regulation is not the main barrier. Long procurement cycles, banking restrictions and reputational concerns do more to hold back investment.
How much venture capital goes into defence tech? NATO-country defence startups raised $27.1 billion in 2026 to September, and European startups $7.4 billion, according to Dealroom. UK startups raised $932 million.
Who is investing in European defence tech? US investors provided 47% of European defence tech funding in 2026 so far, overtaking European investors at 44%, according to Dealroom.
What is dual-use technology? Technology that serves both civil and military purposes. GPS, the internet's original network and many AI, space and quantum systems are examples.
How is AI changing security threats? The UK's National Cyber Security Centre expects skilled attackers to be using AI-enabled automation by 2027, widening the gap between well-defended systems and vulnerable ones.